SoFi Tie-up Shows Stablecoins Can Provide Alternative Blockchain Settlement Rail
SoFi is migrating its entire card program, expecting $25 billion in annualized volume, to blockchain-based settlement using its SoFiUSD stablecoin with Mastercard. This shift provides an alternative settlement rail without changing how consumers pay.
Intelligence analysis by Gemini 2.5 Flash
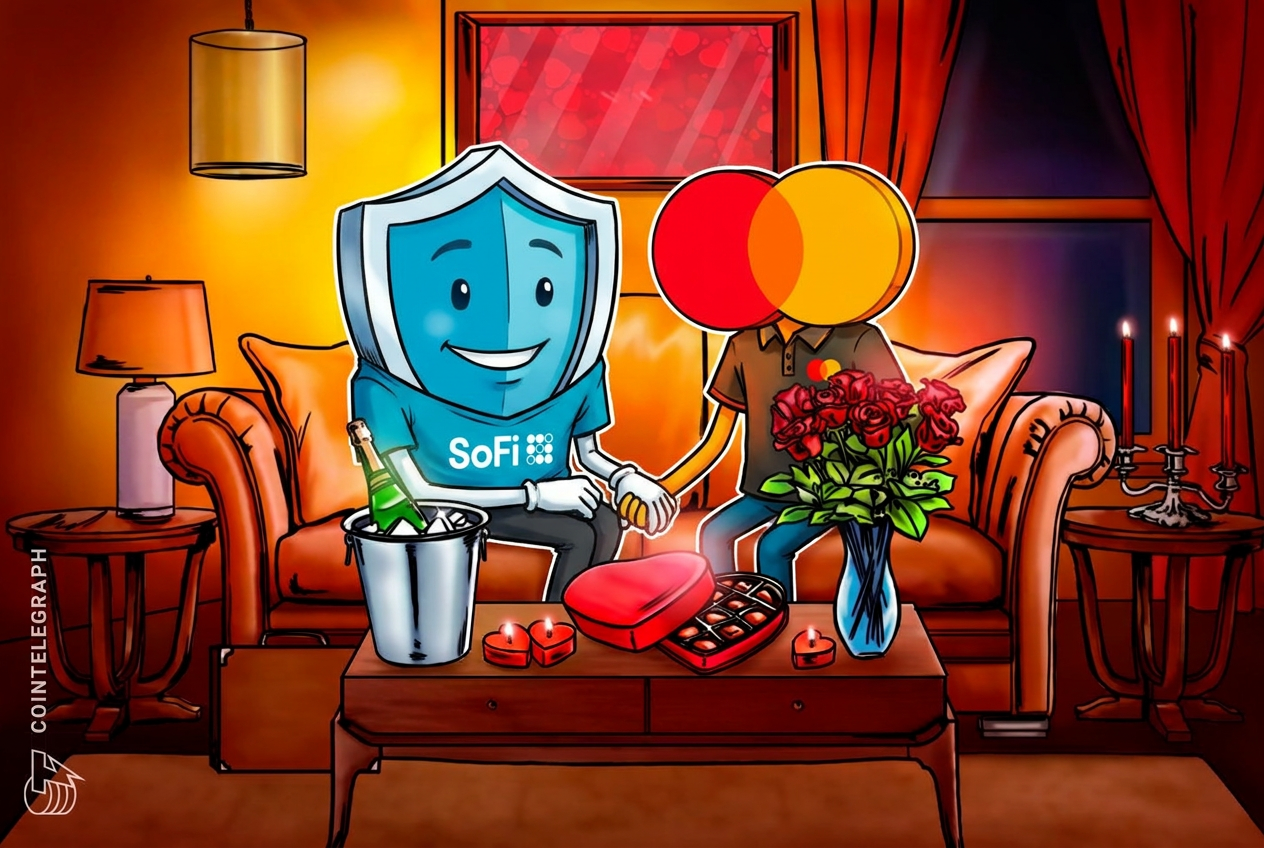
SoFi has partnered with Mastercard to move its substantial card program onto a blockchain-based settlement system utilizing its proprietary SoFiUSD stablecoin. This initiative aims to leverage stablecoins for faster, round-the-clock settlement of transactions, integrating crypto technology into traditional payment networks without disrupting the consumer experience or eliminating exis…
Imagine when you buy something with your debit card, the money usually takes a little while to fully move from your bank to the store's bank. SoFi, a big money company, is now using special digital money called "stablecoins" to make that transfer happen super fast, like almost instantly, even though you still use your regular card. It's like upgrading the secret roads the money travels on to a super-highway, but you still drive your same car.
Analysis
The integration of stablecoins into traditional payment infrastructure marks a pivotal moment for the cryptocurrency ecosystem, demonstrating a practical application beyond speculative trading. SoFi's decision to migrate its entire card program, encompassing an anticipated $25 billion in annualized volume, to a blockchain-based settlement system using its SoFiUSD stablecoin with Mastercard, underscores a growing recognition of stablecoins' utility. This move is not about disintermediating established players like Visa or Mastercard, but rather about optimizing the underlying settlement rails. It allows for continuous, round-the-clock settlement, a significant improvement over traditional batch processing, which can reduce delays and the amount of capital financial institutions need to hold in various locations. The shift primarily impacts the backend, making transactions faster and more efficient for the bank, while consumers continue to use their cards as usual. This strategic adoption by a major financial technology company like SoFi, in collaboration with a global payment giant, signals a maturing phase for stablecoin technology, moving it from niche crypto applications to foundational financial infrastructure.
SoFiUSD
SoFi's proprietary stablecoin, SoFiUSD, is central to this new settlement architecture. By leveraging its own dollar-backed digital asset, SoFi gains greater control and potentially more efficient internal processes for managing its card program's settlement obligations. The stablecoin acts as the digital medium for transferring value between participants in the Mastercard network, replacing the slower, traditional banking rails. This internal stablecoin strategy allows SoFi to experiment and innovate within a controlled environment, potentially setting a precedent for other financial institutions considering similar integrations. The expected $25 billion in annualized volume processed through SoFiUSD highlights the scale and ambition of this initiative, positioning SoFi as a frontrunner in adopting blockchain for core financial operations.
Mastercard
Mastercard's collaboration with SoFi on this stablecoin settlement program is a clear indication of traditional payment networks embracing blockchain technology. Rather than viewing stablecoins as a threat, Mastercard, much like Visa with its own stablecoin settlement pilot, sees them as a "viable complement to traditional settlement rails." This partnership allows Mastercard to explore and integrate the benefits of blockchain-based settlement, such as speed and continuous operation, into its existing robust network. By facilitating the use of SoFiUSD for card transaction settlement, Mastercard is actively participating in the evolution of payment infrastructure, ensuring its relevance in a rapidly digitizing financial landscape. This strategic alignment suggests a future where traditional and blockchain-native payment systems coexist and interoperate, offering enhanced services to financial institutions and, indirectly, to consumers.
Federal Reserve
The Federal Reserve's perspective, as noted in a March research brief, suggests that stablecoins could fundamentally alter the economics of payments without necessarily eliminating the role of banks. This view aligns with the current implementation by SoFi and Mastercard, where intermediaries remain integral to the process. Federal Reserve researchers acknowledge the potential for stablecoins to improve payment efficiency and reduce costs associated with capital management, particularly for cross-border transactions. However, they also implicitly recognize the complexities involved, such as conversion costs, compliance requirements, and the need for local liquidity. The Fed's ongoing research and cautious optimism indicate that while stablecoins offer significant promise, their full integration into the broader financial system will require careful consideration of regulatory frameworks, economic implications, and operational challenges to ensure stability and consumer protection.
Key points
- SoFi is moving its entire card program, with $25 billion in expected annualized volume, to blockchain-based settlement.
- The settlement will use SoFi's proprietary SoFiUSD stablecoin in partnership with Mastercard.
- This initiative provides an alternative blockchain-based settlement rail, not a replacement for existing card networks or banks.
- The change primarily affects backend processes, allowing faster transaction settlement for the bank.
- Experts note that while stablecoins offer continuous settlement benefits, they don't necessarily lead to cheaper payments due to various associated costs.
- Local currency liquidity and access to domestic banking systems remain crucial for completing stablecoin-based payments in emerging markets.
The move by SoFi and Mastercard could pave the way for broader adoption of stablecoin-based settlement across the financial industry, leading to increased efficiency, reduced capital requirements for firms, and faster global payments. This could solidify stablecoins as a vital infrastructure component, enhancing the overall speed and reliability of financial transactions.
Despite the potential for faster settlement, the article highlights that stablecoin adoption doesn't automatically mean cheaper payments due to conversion, compliance, and integration costs. Furthermore, challenges remain in emerging markets where local currency liquidity can be thin, and access to traditional banking systems is still required to complete payments, limiting the immediate global impact.