UTXO’s Loren Asmus: The $300T Bond Market Is Bitcoin’s Next Frontier
Loren Asmus of UTXO Management views Bitcoin not as a trade, but a structural portfolio allocation due to its risk-adjusted returns. He highlights institutional adoption trends and the critical role of education.
Intelligence analysis by Gemini 2.5 Flash Lite
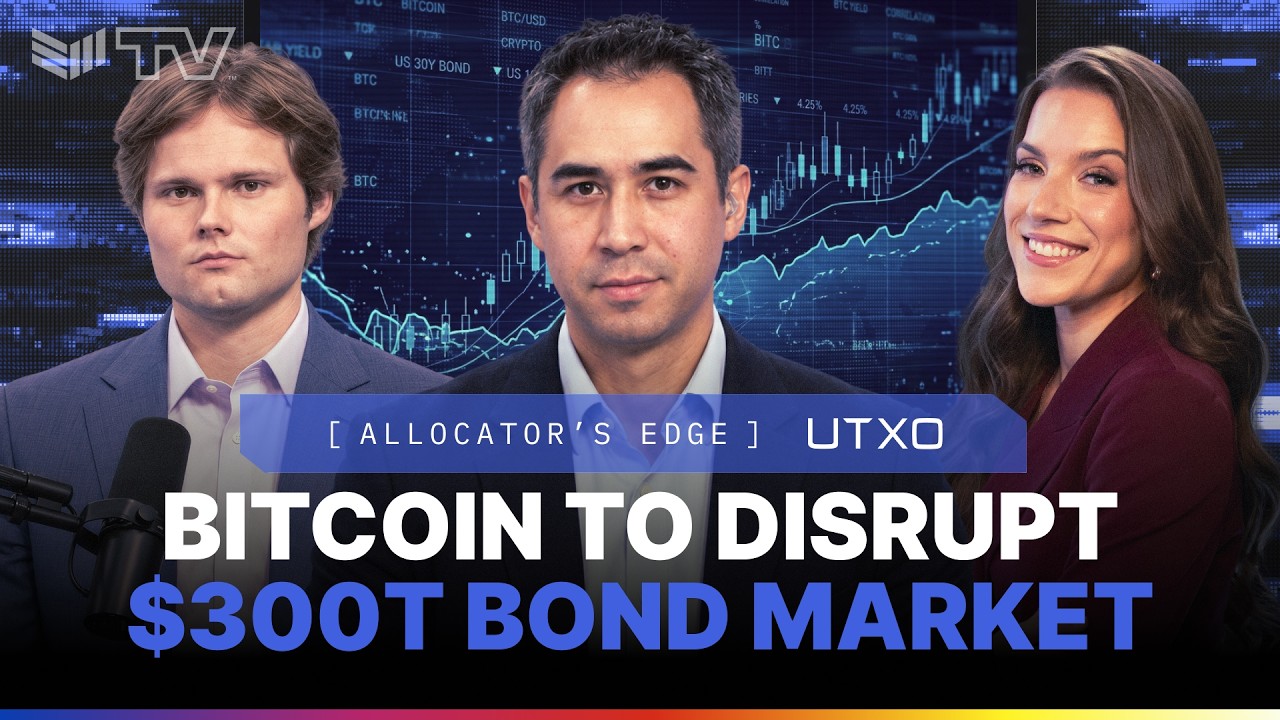
Loren Asmus, from UTXO Management, argues that Bitcoin should be considered a core portfolio asset, not a speculative trade, citing its favorable risk-adjusted returns. He observed at the Bitcoin Treasuries conference that institutions, once invested, tend to remain so, with education being the primary hurdle to broader adoption.
Imagine Bitcoin is like a special kind of digital gold. Instead of just trading it for quick money, big companies are starting to keep it in their piggy banks as a safe place for their money, like a backup plan against money losing its value over time. Learning about it is the hardest part for them.
Analysis
The $300 Trillion Bond Market
Loren Asmus posits that the vast $300 trillion global bond market represents Bitcoin's next frontier for institutional adoption. He draws a parallel between Bitcoin and a credit default swap on debasement, suggesting it acts as a hedge against currency devaluation. This framing is crucial for traditional finance professionals who understand credit risk and sovereign debt. By positioning Bitcoin as a mechanism to protect against the erosion of fiat currency value, Asmus makes a compelling case for its inclusion in portfolios traditionally dominated by fixed-income instruments. The sheer scale of the bond market means that even a small allocation to Bitcoin from this sector could represent a massive influx of capital, fundamentally altering market dynamics.
Institutional Retention and Education
Asmus noted a significant trend at the Bitcoin Treasuries conference: institutions that enter the Bitcoin market tend to stay. This suggests that once the initial hurdles of understanding and integration are overcome, the perceived value proposition of Bitcoin as a long-term asset becomes clear. He identifies education as the primary barrier to entry. This implies that current educational materials and outreach efforts may not be effectively addressing the concerns and knowledge gaps of traditional financial players. Bridging this educational divide is therefore paramount for unlocking further institutional capital and solidifying Bitcoin's role as a legitimate asset class.
Bitcoin as a Portfolio Staple
The discussion reframes Bitcoin from a speculative trade to a strategic portfolio allocation, emphasizing its risk-adjusted returns. Asmus suggests that Bitcoin can fit into a portfolio alongside traditional assets, offering diversification and a hedge against inflation and currency debasement. This perspective challenges the common narrative of Bitcoin as purely a high-risk, high-reward play. The idea of a '2.5% allocation study' points to a growing institutional comfort level with integrating Bitcoin into diversified portfolios. This shift is critical for Bitcoin's maturation, moving it from the fringes of alternative investments to a more established position within mainstream financial planning.
Key points
- Loren Asmus views Bitcoin as a structural portfolio allocation, not a trade, due to its risk-adjusted returns.
- He believes the $300 trillion bond market is Bitcoin's next major frontier for institutional adoption.
- Institutions that invest in Bitcoin tend to remain invested, indicating long-term commitment.
- Education is identified as the main barrier preventing wider institutional adoption of Bitcoin.
- Asmus frames Bitcoin as a credit default swap on debasement, a concept familiar to bond market participants.
If Asmus's view gains traction, Bitcoin could see significant capital inflows from the traditional bond market, leading to increased stability and broader institutional acceptance. This could solidify Bitcoin's role as a legitimate portfolio asset, enhancing its long-term value proposition.
The primary risk is that the educational gap remains too wide, preventing traditional institutions from understanding or trusting Bitcoin as a hedge against debasement. Without this understanding, capital may not flow from the bond market, and Bitcoin could remain perceived as a purely speculative asset.